
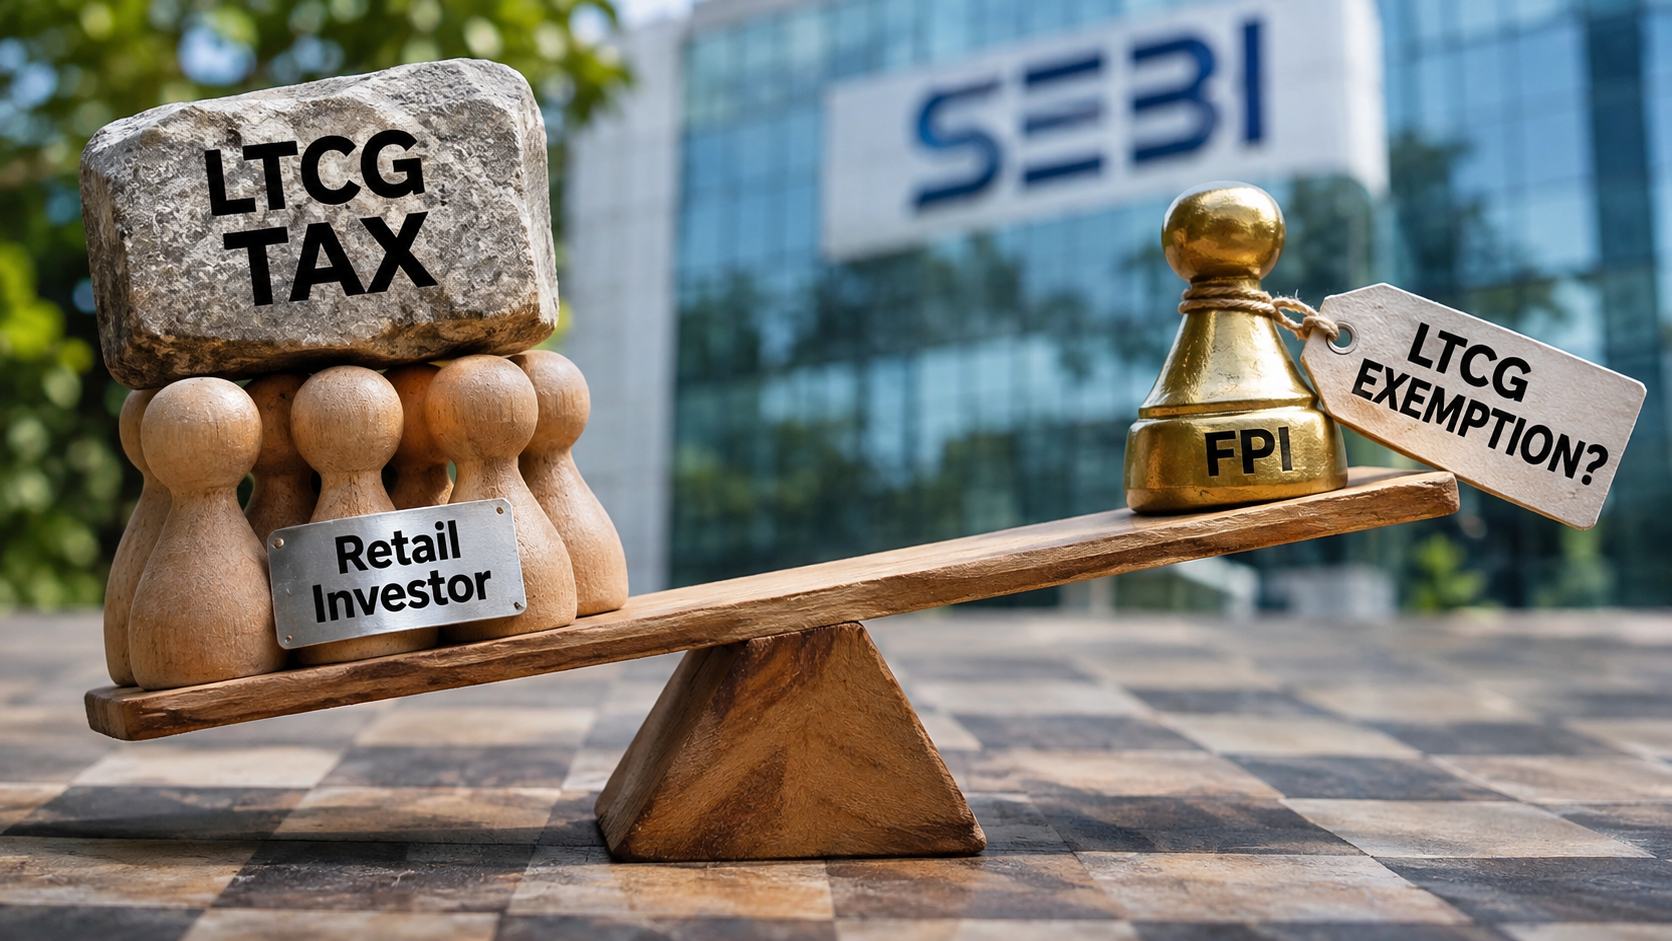
When retail investors are asked to bear the tax burden of investing in India, why should foreign portfolio investors be offered a tax-free exit? And could such a concession create incentives for Indian capital to return home wearing a foreign label?
When the Regulator Becomes the Lobbyist
India’s capital market regulator appears to have found a new prescription for a struggling stock market: remove long-term capital gains (LTCG) tax on foreign equity investors. According to a Reuters report dated November 2, 2026, the Securities and Exchange Board of India (SEBI) has recommended the exemption to the government ahead of the Union Budget 2027. The proposal is reportedly intended to improve India’s attractiveness to foreign capital after sustained portfolio outflows and disappointing market performance.
The economic argument is familiar. Foreign investors are mobile, competing markets offer more favourable tax treatment, and India must improve post-tax returns to attract global money. Yet, beneath this seemingly pragmatic recommendation lies a fundamental question of fairness: should the government grant foreign investors a tax advantage while Indian retail investors continue paying tax on their equity gains?
More importantly, is this genuinely an independent regulatory recommendation, or is the government using the capital market regulator to build a case for a policy concession it would prefer not to defend directly?
Retail Investors: The Convenient Source of Tax Revenue
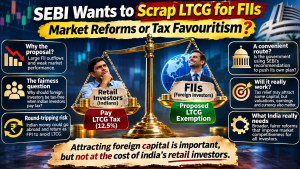
Since July 2024, eligible long-term gains on listed equities exceeding the annual exemption threshold of ₹1.25 lakh have generally attracted LTCG tax at 12.5%. Short-term gains on specified equity transactions are taxed at 20%, subject to applicable provisions. These rates apply to domestic investors and foreign portfolio investors under the current framework.
For retail investors, however, the tax is only one component of an increasingly demanding investment environment. They face market volatility, inflation, transaction costs and the risk of capital erosion. Unlike large institutional investors, small investors often lack the resources to diversify internationally or optimise their tax structures.
Consider a salaried individual investing post-tax savings in equities. Income tax has already been paid on the salary. When the investment eventually produces a qualifying long-term gain, another tax liability arises. If the market falls, the investor bears the loss. If it rises, the government claims its share.
Now consider the proposed alternative: a foreign portfolio investor could potentially realise comparable long-term equity gains without paying Indian LTCG tax.
The distinction is difficult to defend purely on grounds of fairness. Foreign investors also bear market risks, but so do domestic households. If taxation is justified as a contribution to public revenue, why should the origin of investment capital automatically determine whether the investor must contribute?
The government may argue that foreign capital is internationally mobile. That is a legitimate economic consideration, but mobility alone cannot become a permanent passport to preferential treatment.
The Round-Tripping Risk: Indian Money, Foreign Identity
Perhaps the most uncomfortable question concerns round-tripping.
Round-tripping occurs when domestic capital moves abroad, sometimes through complex ownership structures or offshore entities, and subsequently returns to the country as ostensibly foreign investment. Such arrangements can obscure the ultimate beneficial owner and, in certain circumstances, be used to exploit regulatory or tax advantages.
An exemption from LTCG tax specifically for foreign portfolio investors could increase the incentive for some Indian investors to explore such structures. If the same Indian equity investment generates a taxable gain when held directly by a resident but a tax-free gain when held through an eligible foreign investment vehicle, the tax differential creates an obvious incentive to investigate whether the investment can be routed through an offshore structure.
This does not mean that all offshore investments involve round-tripping, nor that every foreign portfolio investor is an Indian investor in disguise. Legitimate international investment serves an important economic purpose. Nor would a tax exemption automatically make an otherwise unlawful structure legal.
Nevertheless, the proposed differential could make beneficial ownership, source-of-funds verification and enforcement more consequential.
The question policymakers must answer is straightforward: if the objective is to attract genuinely incremental foreign capital, how will the government distinguish it from domestic wealth returning through foreign entities primarily to secure a tax advantage?
Without robust beneficial ownership checks, information-sharing arrangements and effective enforcement, a policy designed to attract foreign capital could inadvertently reward the repackaging of domestic capital. India could end up surrendering tax revenue on investments that would have entered the market anyway.
A Regulatory Recommendation That Suits the Government
The institutional optics are equally troubling.
The government determines taxation, frames the Union Budget and ultimately decides whether to grant exemptions. SEBI’s statutory mandate, meanwhile, is to protect investors, promote the development of the securities market and regulate it.
SEBI is entitled to recommend tax reform. Indeed, it should alert the government when taxation undermines market competitiveness. But there is a difference between identifying a problem and prescribing a concession that benefits one investor category.
The reported recommendation arrives at a politically convenient moment. Foreign investors have been selling Indian equities, market performance has disappointed, and the government has repeatedly emphasised the need for equity capital to sustain economic growth. In this context, a proposal from the regulator can provide an independent-looking institutional endorsement for a policy that the government might otherwise have to justify as its own choice.
The concern is not that SEBI has exceeded its authority merely by making a recommendation. It is that the government could use the regulator’s market-development mandate to legitimise a tax preference while avoiding the harder debate over who ultimately benefits and who bears the cost.
This remains a question of institutional accountability, not proof of political orchestration. The reported proposal is non-binding, and the government has not announced that it will accept it. Nevertheless, any eventual decision must be defended by the government on its merits, rather than presented as an unavoidable consequence of market demands.
Will Removing LTCG Bring Foreign Investors Back?
The assumption that tax relief will revive Indian equities deserves scrutiny.
Foreign investors have sold heavily, but taxation is not the only determinant of capital allocation. Valuations, earnings growth, currency movements, geopolitical risks and the relative performance of competing markets all influence investment decisions.
Eliminating LTCG tax could improve post-tax returns. It cannot, by itself, improve corporate profitability, make expensive stocks cheaper or prevent currency depreciation from eroding dollar-denominated returns.
There is also a distinction between attracting foreign portfolio flows and attracting productive capital. Buying existing shares can improve liquidity and price discovery, but it does not necessarily provide fresh capital directly to the underlying company. The broader economic benefits depend on how portfolio flows affect valuations, financing conditions and subsequent investment.
Tax relief may therefore attract some additional capital, but it could also subsidise investment that would have occurred without the concession. The government should establish the likely additional investment and economic benefits before accepting a permanent loss of revenue.
Reform the Market, Not Just the Tax Bill
India needs competitive capital markets, but competitiveness should not mean offering tax concessions whenever investors threaten to leave. A more credible approach would examine the entire investment environment: transaction costs, regulatory predictability, market accessibility, corporate governance and the quality of earnings.
If taxation is genuinely excessive, the government should consider a coherent reform that evaluates the treatment of domestic and foreign investors together. It could also examine whether a broader reduction in the tax burden would encourage household participation and long-term investment without creating an unnecessarily large differential between investor categories.
SEBI has also reportedly recommended relief for domestic mutual fund investors switching between schemes after holding units for more than a year. That proposal deserves separate consideration, particularly if it reduces tax friction and discourages unnecessary withdrawals. However, relief for one category of domestic investors does not automatically justify exempting foreign investors from LTCG tax altogether.
The Final Question: Whose Market Is It?
India’s equity market cannot be built on foreign capital alone. Domestic households contribute savings, sustain systematic investment flows and absorb market risks even during prolonged periods of underperformance. Their confidence is a strategic asset, not a secondary consideration to be sacrificed whenever foreign flows weaken.
If the government concludes that exempting foreign investors from LTCG tax is necessary, it must publish a credible economic justification, assess the revenue implications and explain how it will prevent abuse. It must also confront the fairness question directly: why should an Indian investor pay tax on a qualifying long-term equity gain while an eligible foreign investor pays nothing?
A market reform should strengthen the market without making its domestic participants feel like second-class investors.
The government must decide whether it wants to improve India’s investment fundamentals or simply make the tax bill more attractive to foreign capital. If the latter becomes the preferred strategy, the risk is that India will reward the label attached to the money rather than the economic value it creates.
And if domestic money can potentially travel abroad, return under a foreign identity and obtain a tax advantage unavailable to the original investor, the policy could create precisely the wrong incentive.
India needs foreign capital. But it also needs tax fairness, regulatory independence and public confidence. None should be treated as expendable merely to persuade investors to stay.